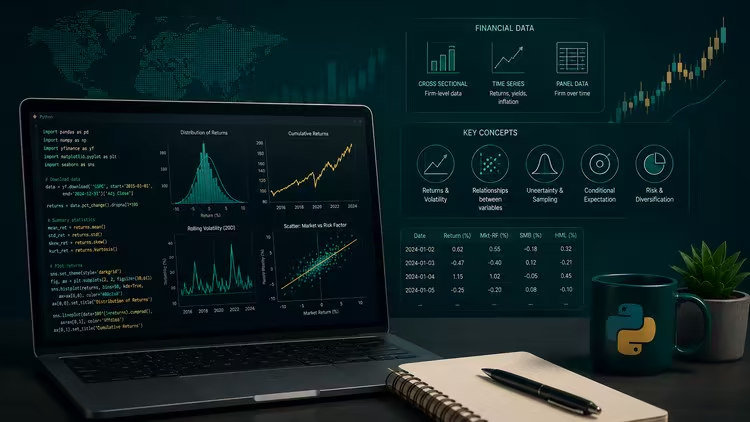
 Free Download Foundations for Financial Modeling Econometrics Basics
Published 5/2026
MP4 |
Video: h264, 1920x1080 |
Audio: AAC, 44.1 KHz, 2 Ch
Language: English |
Duration: 2h 46m |
Size: 978.78 MB
Learn the foundations of financial econometrics & financial data analysis for financial modeling & quantitative finance
Understand what financial econometrics is and how it differs from statistics, machine learning, and traditional financial analysis.
Identify different types of financial data such as cross-sectional data, time series, and panel data used in financial modeling.
Understand randomness, noise, and uncertainty in financial markets and why financial data behaves differently from physical systems.
Interpret mean return, volatility, covariance, and correlation in the context of financial markets and portfolio analysis.
Understand the concept of conditional expectation and why it forms the foundation of regression and financial modeling.
Understand sampling uncertainty, standard errors, and confidence intervals in financial estimation.
Apply basic financial data analysis using Python through simple hands-on labs and examples.
RequirementsBasic understanding of finance concepts such as returns and markets is helpful but not required
Basic familiarity with Python is useful for the lab sessions
No prior knowledge of econometrics is required
A computer with Python installed (Anaconda or Jupyter Notebook recommended)
DescriptionFinancial markets generate massive amounts of data every day. Prices move constantly, returns fluctuate, volatility changes, and relationships between financial variables evolve over time. Understanding these patterns is the goal of
financial econometrics.
However, many econometrics courses feel overly mathematical and disconnected from real financial markets.
This course takes a different approach.
Instead of focusing on complex formulas, we focus on
building intuition about financial data and the statistical ideas behind financial modeling.
This course is
Stage 0 of the Applied Financial Econometrics learning path and is designed to build a strong conceptual foundation before moving to more advanced econometric models.
Throughout the course, we will explore questions such as
• Why do financial markets look noisy?
• What makes financial data different from other types of data?
• What do mean return and volatility actually represent?
• Why is correlation important in portfolio construction?
• What does randomness really mean in financial markets?
• Why are financial estimates always uncertain?
You will learn how to think about financial data from an econometric perspective while developing an understanding of the key statistical ideas used in financial modeling.
To make these ideas practical, the course also includes
Python-based examples and simple labs where we explore financial data and visualize important concepts.
The goal of this course is not to overwhelm you with mathematics, but to help you
develop intuition about financial data, uncertainty, and relationships between variables in financial markets.
In this course you will learn• The role of econometrics in financial modeling
• Different types of financial data used in quantitative finance
• Why financial markets exhibit randomness and noise
• The meaning of mean return, volatility, covariance, and correlation
• The concept of conditional expectation and why it underlies regression models
• How sampling and uncertainty affect financial estimates
• How to explore financial data using Python
Who this course is forStudents studying finance, economics, or quantitative finance
Learners interested in financial data analysis and financial modeling
Aspiring quantitative analysts or financial data scientists
Anyone who wants to understand the statistical foundations behind financial models
Recommend Download Link Hight Speed | Please Say Thanks Keep Topic Live
No Password - Links are Interchangeable

 Cantinho Satkeys
